

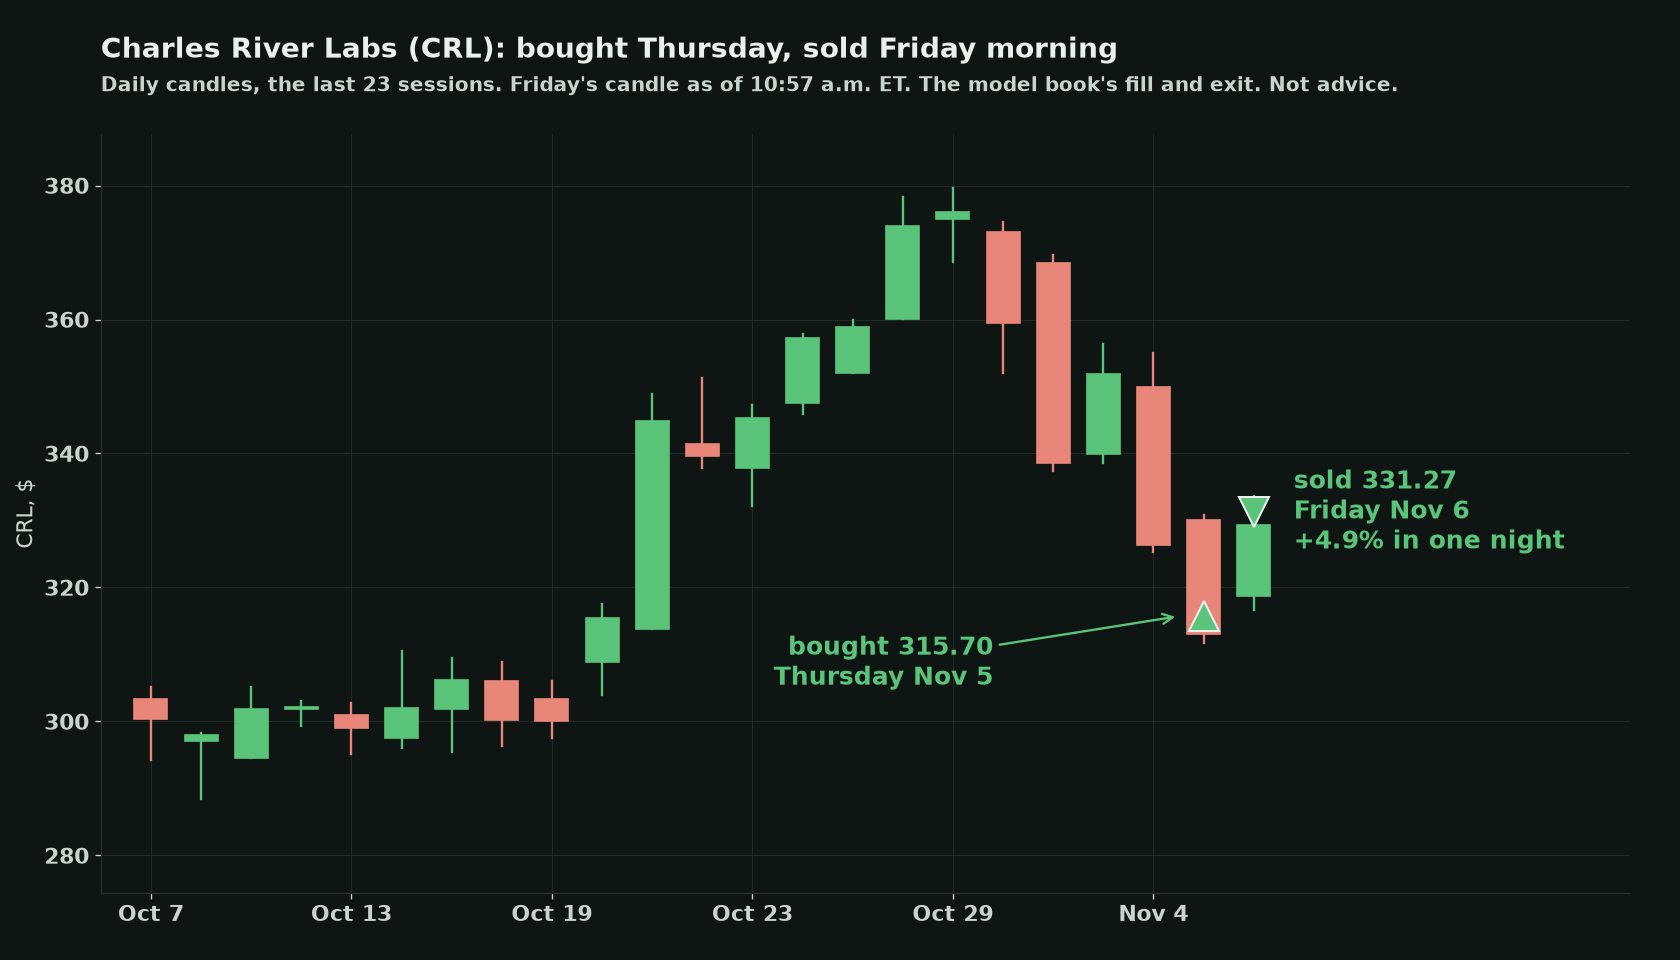
So, it was a rough week. The S&P 500 fell 4.4% on Thursday, its biggest one-day drop since April of last year. That same day our buy limit on Charles River Labs, from Wednesday night's sheet, filled at 315.70. Friday morning it hit the target at 331.27, fourteen minutes after the open. Up 4.9% in one night.
The setup: Wide Mean Reversion
Here is what it looks for. A liquid, fast-moving stock that is still in a long-term uptrend, after a sharp slide over a few days and one more hard down day. We rest a buy limit under that close for one session. If it does not fill, there is no trade. If it fills, the exit is already written: a profit target from the next morning, or a dated sale at the open two sessions later. It is a one or two night trade.
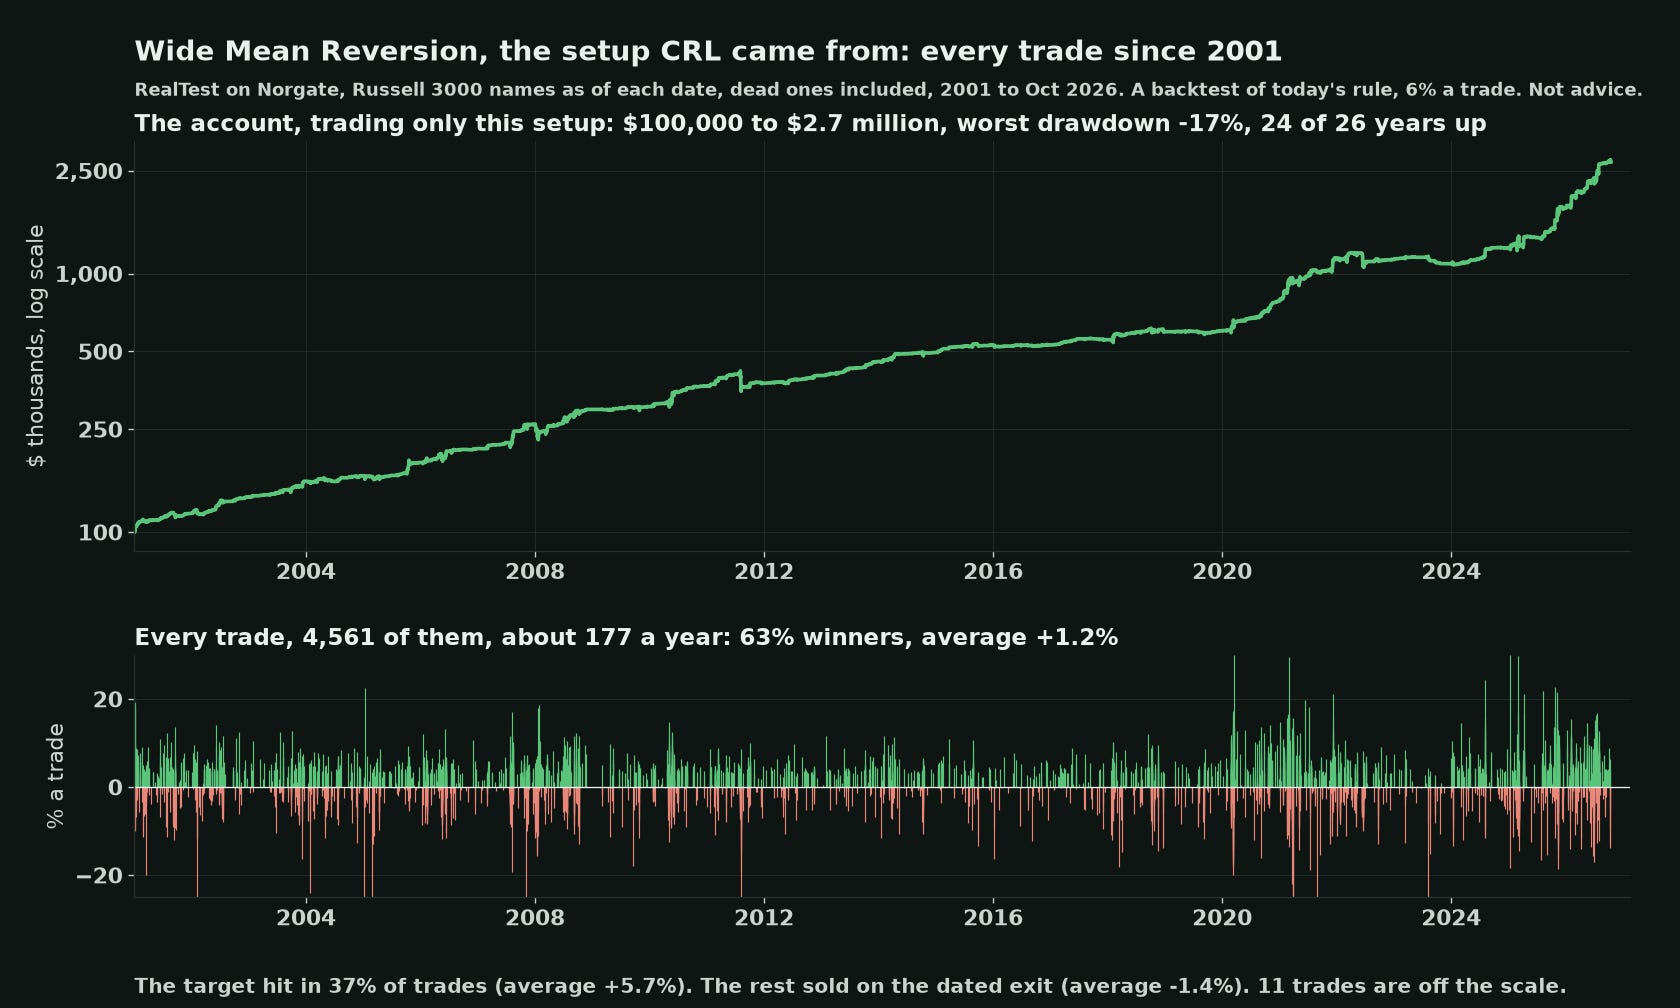
That is every trade since 2001 in a backtest of today's rule. 4,561 of them, about 177 a year. 63% winners, average +1.2% a trade. The target hits a bit more than one time in three, and those average +5.7%. The rest get sold on the dated exit and average -1.4%. 24 of 26 years up. Run on its own with 6% of the account a trade, the backtest makes about 13.5% a year with a worst drawdown of 17%.
Live is younger and rougher. We have traded it for members since late September: 35 closed trades, 18 up, average -0.3%. A small edge needs a lot of trades, and a week like this one is where the buys come from.
You can trade this by hand. Find the strong stocks that just got hit, rest the limit, write the exit before you buy, and take every one, because you do not know ahead of time which one is the CRL.
Or you pay me $150 a month and I give you the trades every night, with the target and the date. Come on over: Stats Edge, the full sheet
Until next time, get away from the screens.
Michael